3:07:35 PM | 7/10/2026

Thien Viet Securities (TVS) has officially released the Vietnam Financial Health & Investment Confidence Report 2026. The report provides a data-driven view of asset allocation, wealth resilience, investment confidence, and preparedness for long-term financial planning among individual investors in Vietnam.
Wealth resilience: Portfolios remain concentrated in familiar assets
Amid ongoing market volatility and rising living costs continuing to affect financial decisions worldwide, financial resilience is becoming an important measure alongside asset size. In Vietnam, TVS’s survey shows that investors are actively participating in multiple investment channels, with 55% holding 2 to 3 investment channels and 39% holding 4 to 5 channels. However, in terms of actual allocation, bank deposits, gold, and real estate still account for 87% of the total asset portfolio of surveyed individual investors.
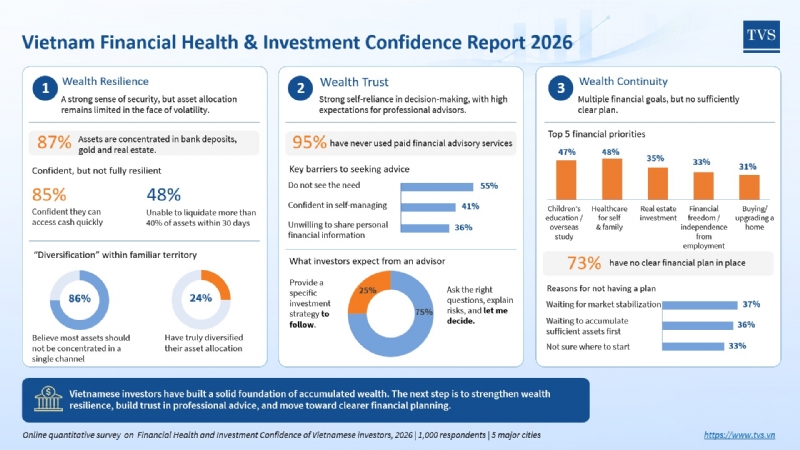
This infographic summarizes the key findings from the "Vietnam Financial Health & Investment Confidence Report 2026," based on a survey of 1,000 respondents in 5 major cities, conducted by TVS
This concentration becomes more pronounced among investors with larger asset bases. As accumulated wealth increases, the proportion of real estate in the portfolio rises from 29% among those with VND 500 million to under VND 1 billion, to 46% among those with VND 2 billion or more. By contrast, the combined allocation to modern financial channels such as equities, bonds, fund certificates, and foreign currency remains low, not exceeding 10% across any asset group.
The survey also highlights a gap between awareness and action in portfolio diversification. While 86% of respondents agree that most assets should not be concentrated in a single channel, 76% still prioritize real estate or gold because they feel they understand these channels better. This suggests that the need for diversification is recognized, but actual allocation behavior remains strongly shaped by familiar assets.
Financial resilience is also gaining broader attention across the region. In Hong Kong, Sun Life’s Financial Resilience Index 2026 found that 51% of respondents would be unable to sustain themselves financially for more than 6 months if they lost their income or had no external support. In Vietnam, TVS’s survey shows that 85% of investors believe they can access cash quickly when needed, yet nearly half of respondents can liquidate no more than 40% of their assets within 30 days.
These findings suggest that financial resilience depends not only on asset size, but also on liquidity, risk allocation, household cash flow, and the ability to adapt to market volatility.
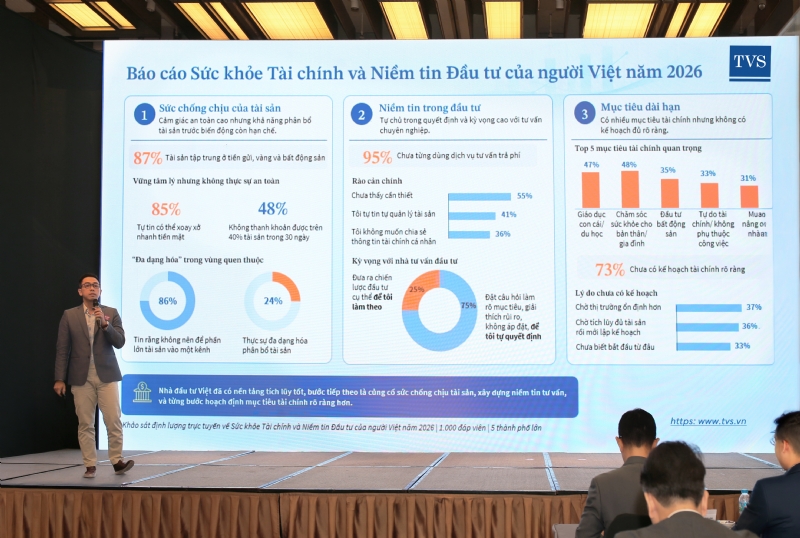
Mr. Le Pham Minh Duc, Senior Director, Investment Banking Division at TVS, expects this report to help investors view assets more comprehensively, not only in terms of accumulation scale but also in terms of resilience, risk allocation capabilities, and preparation for long-term goals
Wealth trust: Investors seek guidance, not prescription
Globally, market uncertainty and cost pressures are increasing investors’ demand for safety and professional advice. According to Natixis Investment Managers’ 2025 survey of more than 7,000 individual investors, 73% of investors prioritize safety over investment performance, 66% are saving less due to rising living costs, and 91% trust financial advisors when making investment decisions. In Vietnam, TVS’s survey also points to an underlying need for guidance in wealth management, yet the use of paid financial advisory services remains very limited, with 95% of respondents saying they have never used such services.
The main barrier is not cost, but the perceived practical value of professional advisory services: 55% say they have not seen the need, 41% are confident in managing their assets independently, and 36% are unwilling to share personal financial information. Nevertheless, investors’ trust in financial institutions has not disappeared. Rather, it is shifting toward higher expectations for transparency and advisory quality. Among those who have used or are using paid financial advisory services, 75% expect advisors to ask the right questions, clarify goals, explain risks, and support investors in making their own decisions. Only 25% prefer to be given a specific investment strategy to follow.
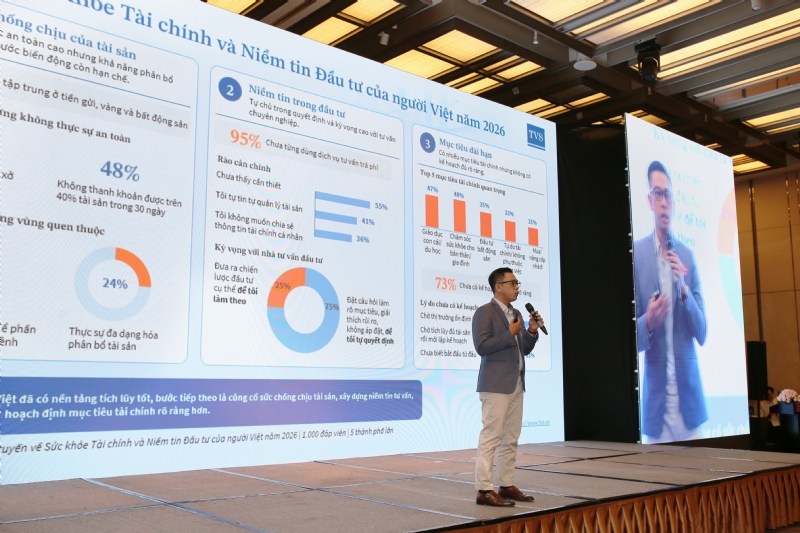
Mr. Tran Vinh Quang, CEO of Thien Viet Asset Management (TVAM), commented: “As investors become increasingly proactive in managing their wealth, the role of financial institutions is no longer limited to providing products or investment recommendations. It is about building a transparent, data-driven advisory process tailored to each client’s goals. Trust is built when investors can clearly see the practical value of professional advice: helping them understand risks, validate decisions, and maintain long-term financial discipline.”
Wealth continuity: From asset accumulation to proactive planning
The report also highlights a gap between the desire to accumulate assets and the proactive development of long-term financial plans. Only 27% of surveyed investors say they have a clear long-term financial plan for themselves and their families. The remaining 73% have either not started, have not defined their goals, or do not yet have a specific roadmap. Investors’ financial priorities also reflect the central role of family in asset-related decisions. When asked to select their most important long-term financial goals, healthcare for self and family and children’s education or overseas study ranked as the top two priorities, at 48% and 47% respectively. These were followed by real estate investment (35%), financial freedom or independence from employment (33%), and buying or upgrading a home (31%). As multiple long-term goals coexist, having a clear plan becomes essential for investors to allocate resources more effectively across different stages of wealth accumulation.
Notably, wealth transfer is still not viewed as a financial goal requiring proactive planning. Although real estate and ancestral/family assets play an important role in the wealth-accumulation mindset of many Vietnamese families, only 8% of respondents included wealth transfer among their top financial goals. This reveals a gap between the desire to pass assets on to the next generation and the preparation of a concrete plan to preserve, allocate, and transfer wealth effectively.
Mr. Le Pham Minh Duc, Senior Director, Investment Banking Division, TVS, commented: “Globally, wealth management is moving beyond the pursuit of returns alone toward risk management, asset preservation, and preparation for long-term goals. Vietnamese investors are following the same direction, while retaining distinct characteristics as portfolios remain concentrated in traditional channels. From TVS’s perspective, this report provides practical data to help investors assess their wealth not only by accumulated size, but also by resilience, risk allocation, and preparedness for their families’ long-term goals.”
By Viet Business Forum